Storms don't ask permission in Oklahoma. They just show up.
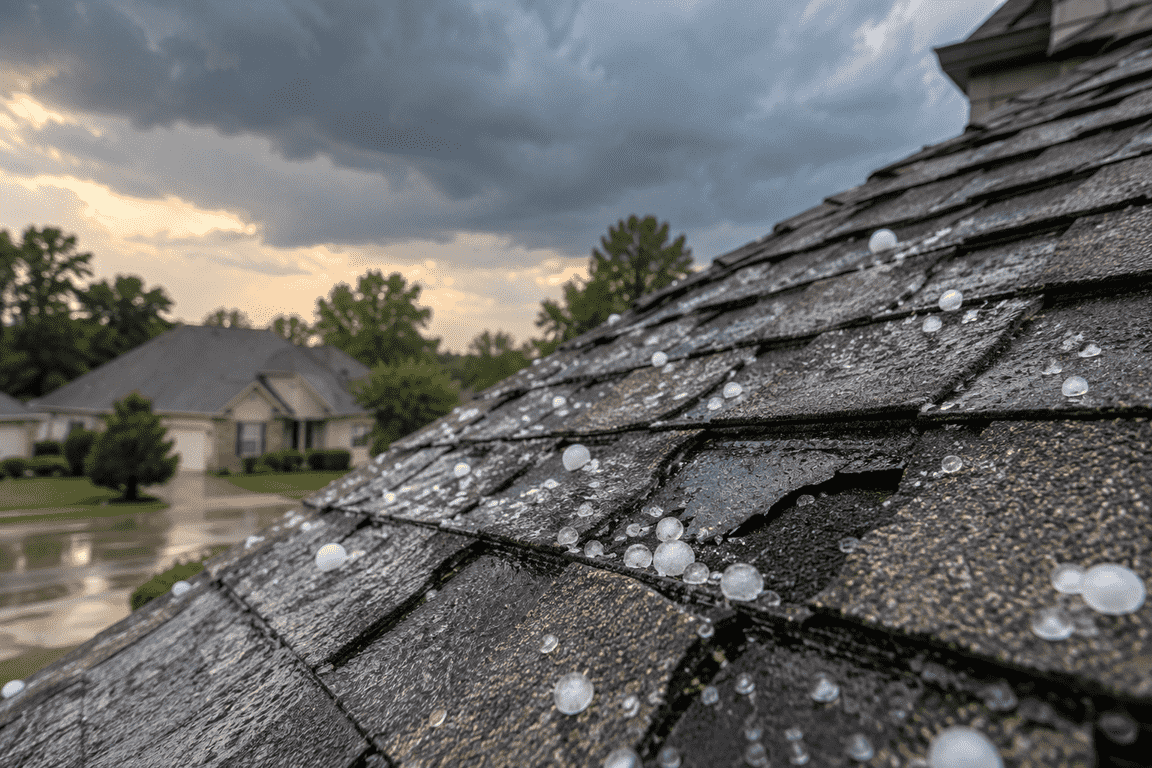
In 2026, the Oklahoma Insurance Department dropped a number that should stop every homeowner mid-scroll: nearly half of Oklahoma roofs took a hail hit over the past four years. Not "some." Not "a few unlucky neighborhoods." Half.
So the question isn't rhetorical anymore. Does homeowners insurance cover hail damage?
Usually, yes. Most standard policies pay out for hail damage to your roof and other parts of your home. But "usually yes" isn't the same as "automatically, no questions asked." Deductibles, exclusions, roof age, and how your policy values the damage all decide what actually lands in your bank account after the storm passes.
Oklahoma homeowners who wait until the sky turns green to learn these details are already behind.
Does Homeowners Insurance Cover Hail Damage in Oklahoma?
Wind and hail damage to your roof? Standard policies generally cover it.
But homeowners insurance hail damage coverage isn't a blank check. Every policy has fine print, and the fine print is where claims get denied or shrunk. Watch for:
- Separate wind or hail deductibles
- Cosmetic damage exclusions
- Actual cash value payouts on an aging roof
- Limits on specific roofing materials
- Strict rules about how the damage happened and how bad it is
Don't assume your neighbor's policy works like yours. Hail damage insurance in Oklahoma isn't one-size-fits-all — it's one policy at a time.
Oklahoma Insurance Connection reviews homeowners insurance coverage line by line, so you know exactly what you're holding before you need it.
How Does Roof Damage Insurance in Oklahoma Work?
Here's where two homeowners with the same storm get two very different checks: how the insurer values the roof.
Replacement Cost vs. Actual Cash Value
Replacement cost coverage pays what it costs to repair or replace your roof with comparable materials, within your policy's terms and limits. Some insurers cut a depreciated check up front, then release the rest once the work is done.
Actual cash value coverage does the opposite — it bakes depreciation in from the start. The older your roof, the bigger the gap between what you get and what a new roof actually costs.
Two Tulsa homeowners can survive the identical hailstorm and walk away with wildly different settlements. Same storm. Different policy. Different outcome.
When you're comparing Tulsa roof insurance coverage, the premium is the least interesting number on the page. Ask how the roof gets valued. Ask what the wind and hail deductible actually is.
Pay Attention to Your Wind and Hail Deductible
Some policies charge a flat deductible for wind and hail. Others calculate it as a percentage of your home's insured value — and that percentage can hit a lot harder than it sounds.
A 2% deductible on a $300,000 home isn't $2%. It's $6,000, out of your pocket, before insurance pays a dime.
Before storm season rolls in, know the answers to five questions:
- Is wind and hail covered?
- Do you have a separate wind/hail deductible?
- Are roof claims settled at replacement cost or actual cash value?
- Do cosmetic damage exclusions apply?
- Are there limitations tied to your roof's age?
An independent insurance agency in Tulsa can walk you through every one of these — and shop your coverage across multiple carriers while they're at it.
What Should You Do After a Hailstorm in Tulsa?
Check your property. Stay off the roof.
Look for the obvious tells: missing or damaged shingles, dented gutters or metal surfaces, damaged siding, broken windows, water finding its way inside.
If you spot damage, move fast:
- Photograph and video everything.
- Note the date and approximate time of the storm.
- Take reasonable steps to stop the damage from spreading.
- Save every receipt for emergency repairs.
- Check your deductible and coverage.
- Call your insurance company or agent.
- Get a reputable professional to inspect the roof.
The Oklahoma Insurance Department wants roofs inspected after major hail or wind events, full stop. And Oklahoma law accounts for the fact that wind and hail damage isn't always visible from the ground — but that's not an excuse to sit on it. Report it, and follow your policy's requirements to the letter.
Not All Roof Problems Are Storm Damage
Insurance covers sudden loss. It doesn't cover neglect.
A roof that's simply worn out, installed wrong, or ignored for a decade doesn't become a covered claim just because a storm made it obvious. That's not damage. That's overdue maintenance wearing a storm's name tag.
This is the line that matters most in storm damage insurance in Oklahoma: insurance handles the sudden and covered. You handle the ongoing and expected.
Inspect your roof regularly. Fix small problems before a storm turns them into big ones.
Can a Stronger Roof Help Oklahoma Homeowners?
You're not powerless here. You can build for the next storm before it arrives.
Impact-resistant roofing materials hold up better against hail — and plenty of insurers reward that with a discount. Oklahoma's Strengthen Oklahoma Homes program pushes the same idea at the construction level: build and re-roof to standards that actually survive high wind and hail.
Thinking about a new roof? Ask your agent first whether impact-resistant materials or stronger construction standards could shave money off your premium.
And don't stop at the roof. Standard homeowners policies don't touch flooding — that's a separate conversation. Oklahoma Insurance Connection covers both home insurance and flood insurance options.
Review Your Oklahoma Homeowners Insurance Before the Next Storm
Don't learn your coverage the hard way.
Read your policy now — deductible, roof valuation, exclusions, limits, endorsements, all of it. Ten minutes today saves you a fight tomorrow.
Oklahoma Insurance Connection helps Tulsa-area and Oklahoma homeowners compare personal insurance options and actually understand what they're paying for.
Not sure how your policy handles hail, wind, or roof damage? Contact Oklahoma Insurance Connection and get a real answer before the next storm gives you one.